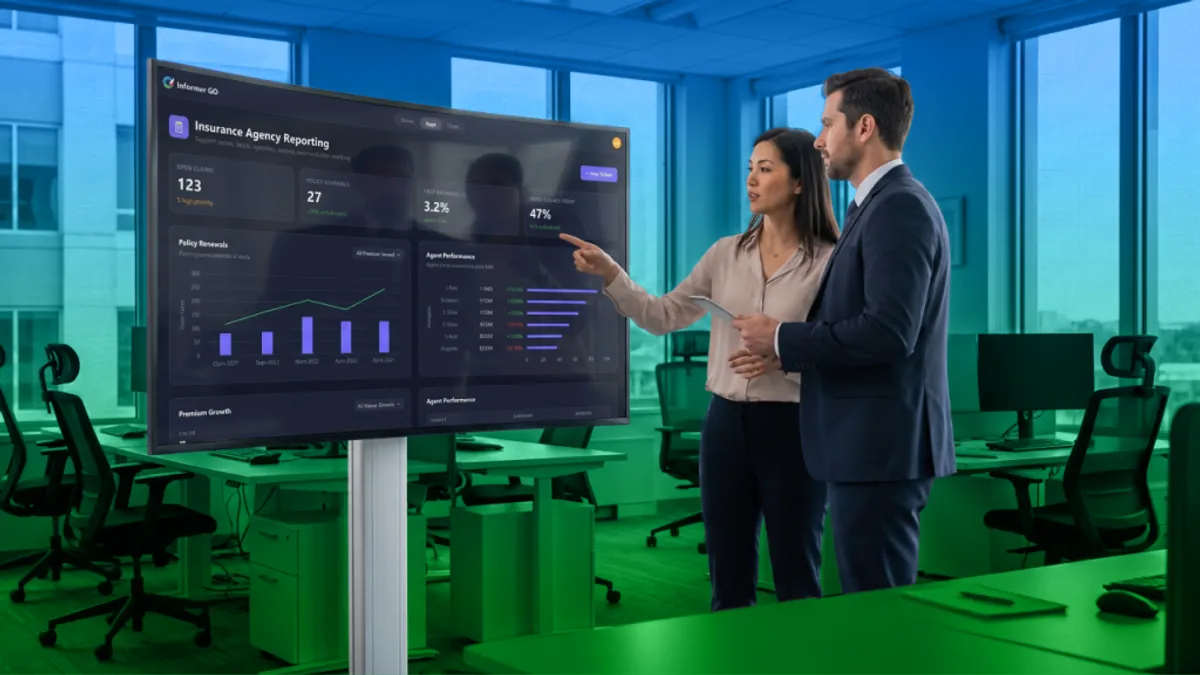
In a changing insurance market, client retention isn’t just a relationship challenge. It’s a visibility challenge.
For years, insurance agencies have relied on relationships to protect their books of business. That still matters, but the market is becoming too dynamic to rely on relationships alone.
The U.S. commercial P&C market is also becoming increasingly uneven. According to Alera Group’s 2026 Midyear Market Update, average commercial insurance premium growth flattened to just 0.2% in the first half of 2026, the softest market conditions seen since 2017. Yet that doesn’t mean every client is seeing relief. Commercial Auto and Umbrella/Excess Liability continue to experience elevated rate increases, while other lines are becoming more competitive.
For agency principals, that creates a different kind of retention challenge.
Some clients will see meaningful increases. Others may suddenly have more competitive options. The agencies best positioned to retain them won’t necessarily be the ones with the lowest premiums. They’ll be the ones that know which relationships need attention before the renewal conversation begins.
Why Insurance Client Retention Starts With Visibility
A client rarely becomes a retention risk overnight. The warning signs often emerge gradually, appearing across several areas of the relationship:
- Engagement may decline
- A client may begin questioning coverage or pricing
- Their account may become less profitable
- A renewal may be approaching with a significant premium change
A previously stable relationship may start showing anyone of the above patterns that deserve attention. The problem is that these signals often exist across different pieces of agency data.
When they’re buried in reports, spreadsheets, or disconnected systems, identifying the accounts that need attention becomes difficult. By the time a client says they’re considering another agency, the most valuable opportunity to influence that decision may already have passed.
The Accounts Most at Risk May Already Be in Your AMS
Your AMS contains much of the information needed to identify potential retention risks: policy history, renewals, premiums, producers, lines of business, and client activity.
The challenge is turning that information into something leadership can act on.
Instead of reviewing retention after the fact, agencies can begin asking more forward-looking questions:
- Which accounts are approaching renewal with significant premium changes?
- Which clients have shown declining engagement?
- Where are retention rates changing by producer or line of business?
- Which accounts represent the greatest revenue risk?
These aren’t simply reporting questions; they’re early-warning questions.
The difference matters because knowing which clients have already left is useful for understanding performance. Knowing which clients may be at risk gives the agency an opportunity to influence the outcome.
From Retention Reporting to Retention Action
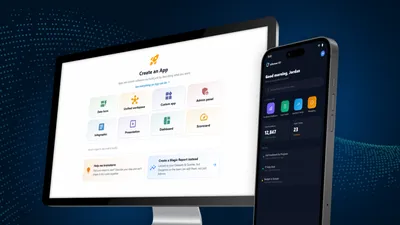
This is where Informer can change the role of reporting. Rather than waiting for a retention report at the end of a reporting cycle, agencies can build real-time dashboards and purpose-built applications around the indicators that matter to their business.
Informer connects directly with AMS360, Applied Epic, Sagitta, and more, allowing agencies to work with live operational data rather than relying on manual exports and disconnected spreadsheets. Informer Apps can then turn those data points into applications designed around specific agency workflows.
An agency could create a retention dashboard that highlights accounts approaching renewal, identifies significant changes, and gives teams a clear view of where proactive outreach may be warranted.
The goal isn’t to predict exactly which client will leave; it’s to make sure your team knows where to look before the client makes the decision for you.
The Future of Insurance Client Retention is Proactive
Retention has traditionally been measured as an outcome: how many clients stayed, how many left, and how the book changed over time.
The opportunity now is to treat retention as something agencies can actively manage.
When agencies can see emerging risk earlier, producers can have more informed conversations. Operations teams can prioritize the accounts that need attention. Leadership can understand where the greatest exposure exists across the book.
That changes the role of agency data. It stops being a record of what happened and becomes a way to decide where attention is needed next.
Ready to move faster, see further, and work smarter? Let’s talk.